Mastering effective money saving tips begins with understanding your daily cash flow and establishing habits that build long-term financial security. Money saving tips are practical, actionable strategies designed to help individuals retain a larger portion of their income rather than spending it immediately. In today’s economic climate, having a reliable financial buffer can significantly reduce everyday stress and provide a safety net for unexpected events. Whether you are funding an emergency reserve, planning for a major life purchase, or preparing for retirement, implementing smart money saving tips requires structure, patience, and realistic budgeting. According to recent consumer financial trends for 2026, structured micro-savings approaches are growing rapidly among households looking to combat inflation. This guide explores fifteen essential money saving tips to help you optimize your personal finances.
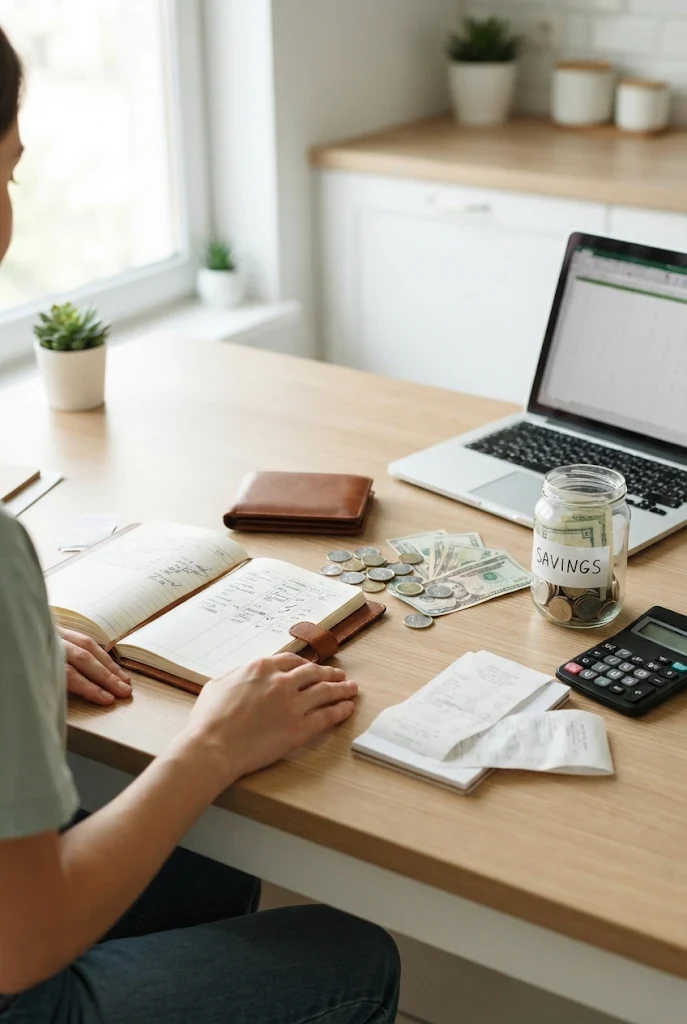
1. Track Every Expense for 30 Days — money
Expense tracking is the foundational step among all money saving tips, providing a clear audit of where your cash actually goes each month. When you log every single transaction—from morning coffee runs to utility bills—you eliminate the blind spots that quietly drain your checking account. For example, spending five dollars daily on convenience items adds up to roughly one hundred and fifty dollars monthly, which could otherwise jumpstart your savings.
The primary benefit of meticulous expense tracking is complete financial awareness, allowing you to spot unnecessary subscriptions and impulse buys immediately. However, the trade-off is the manual effort required to log purchases daily, which can feel tedious if you do not use automated tools. To make this easier, you can rely on a dedicated budgeting app or a standard spreadsheet. The key takeaway is that you cannot optimize what you do not measure, and a single month of tracking often reveals dozens of hidden opportunities to retain more income.
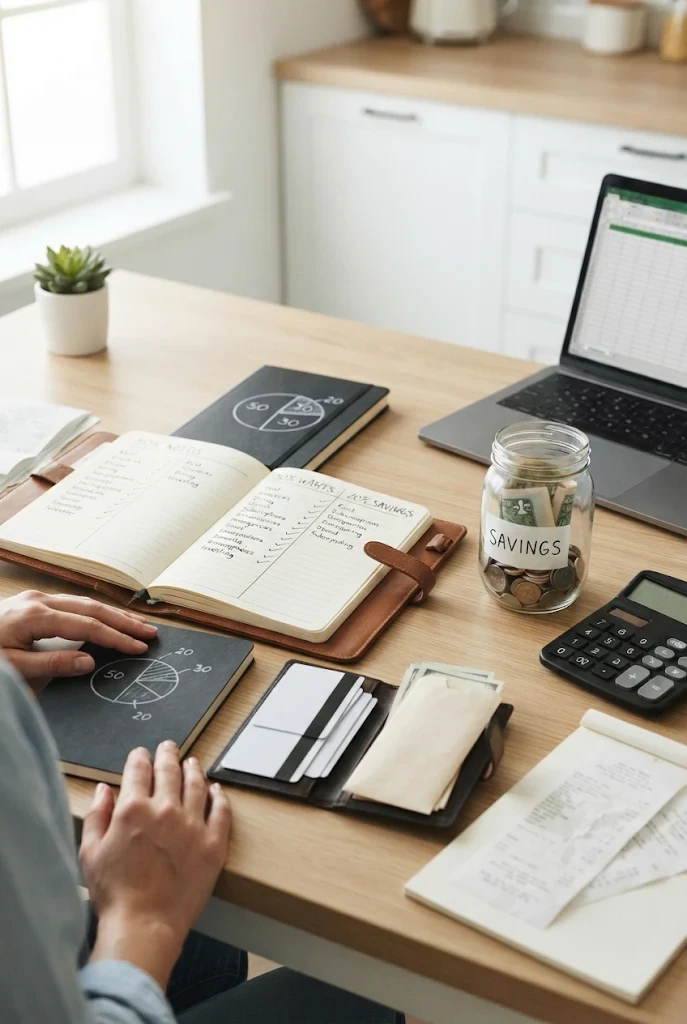
2. Implement the 50/30/20 Budgeting Framework — money
Structuring your net income around a percentage model is a reliable way to balance lifestyle enjoyment with aggressive money saving tips execution. Under this framework, 50% of your net income covers essential needs like housing and groceries, 30% goes toward discretionary wants, and the remaining 20% is dedicated directly to financial priorities and debt reduction. For example, if your monthly take-home pay is four thousand dollars, you would allocate eight hundred dollars specifically to your financial goals.
This method offers the distinct advantage of simplicity and structural flexibility, ensuring you never neglect your future while still enjoying your present life. On the downside, rigid percentage splits may not work for individuals living in high-cost-of-living areas where housing alone consumes more than half of their earnings. Rates, rules, and taxes differ by country and state, so you should adjust these percentages to fit your local cost structure. The key takeaway is that having a predetermined mathematical boundary prevents lifestyle creep and keeps your priorities front and center.
3. Automate Your Transfers on Payday — money
Removing human friction from the equation is one of the most effective psychological money saving tips for achieving consistent outcomes. By setting up an automatic transfer from your checking account to a designated savings account the moment your paycheck lands, you pay yourself first before discretionary spending can occur. For example, instructing your bank to move two hundred dollars into savings every alternate Friday ensures the cash is out of sight and out of mind.
Automation guarantees consistency and removes the temptation to spend money that appears available in your primary account. However, a potential risk is accidentally overdrawing your checking account if your cash flow fluctuates or if unexpected bills hit simultaneously. You must carefully monitor your baseline balances to avoid overdraft fees. The key takeaway is that automation bypasses willpower entirely, turning a difficult monthly chore into a seamless background habit.
4. Build a Dedicated Emergency Fund
Establishing a separate cash reserve is a vital defensive measure that protects your long-term money saving tips milestones from unexpected life disruptions. An emergency fund typically holds three to six months’ worth of essential living expenses in a liquid account, ready to cover sudden medical bills, car repairs, or job loss. For example, if your monthly baseline expenses equal three thousand dollars, aiming for a nine-thousand-dollar safety net provides a reliable cushion against crisis.
The primary benefit is peace of mind, knowing that a broken appliance or medical emergency will not force you into high-interest credit card debt. The trade-off is that keeping thousands of dollars in cash means missing out on the potentially higher returns offered by the stock market or long-term investments. Additionally, inflation slowly erodes the purchasing power of cash sitting in a standard account. The key takeaway is that emergency funds are not designed to grow wealth aggressively; rather, they are insurance policies that safeguard your broader financial plan.
5. Audit and Cut Recurring Subscriptions
Regularly reviewing digital memberships and monthly recurring bills is a fast way to apply essential money saving tips without altering your daily routine. Many households accumulate forgotten streaming services, unused gym memberships, and premium software packages that renew automatically year after year. For example, canceling three streaming services you rarely watch can instantly recover thirty-six dollars per month, or over four hundred dollars annually.
The advantage of this audit is immediate cash flow relief with zero negative impact on your day-to-day lifestyle. The risk, however, is subscription fatigue or canceling a service you actually utilize during certain seasons, leading to friction if you decide to resubscribe later. When organizing your financial reviews, utilizing a physical notebook or digital checklist can help keep you accountable. The key takeaway is that digital clutter costs real money, and a quarterly purge of recurring charges is a high-return maintenance task.
6. Adopt the 48-Hour Rule for Non-Essential Purchases
Impulse buying is a primary obstacle to executing practical money saving tips, often triggered by clever marketing, emotional stress, or late-night online browsing. The 48-hour rule requires you to wait two full days before completing any non-essential purchase over a predetermined threshold, such as fifty dollars. For example, if you see a gadget online that you instantly want, adding it to a cart and closing the tab gives your rational brain time to override your initial emotional impulse.
This cooling-off period successfully prevents buyer’s remorse and drastically reduces unnecessary retail spending. The trade-off is that waiting can occasionally cause you to miss out on genuine limited-time sales or time-sensitive discounts. The key takeaway is that time is a powerful filter for desire, and most urges to buy fade completely once the initial emotional spike subsides.
7. Master Strategic Grocery Shopping and Meal Planning
Food costs represent one of the most flexible major expenses in a household budget, making grocery optimization a core focus among everyday money saving tips. Adopting habits like planning weekly menus, shopping with a strict list, buying generic staples, and avoiding trips when hungry can dramatically lower your weekly food bill. For example, replacing four restaurant lunches a week with home-cooked meals can save over two hundred dollars a month.
Strategic food management improves your overall health and teaches valuable household organization skills. The primary trade-off is the significant time investment required to plan meals, inventory your pantry, and prep ingredients in advance. The key takeaway is that convenience is expensive, and intentional meal planning turns a recurring financial leak into a predictable, manageable expense.
8. Compare Insurance Policies Annually
Loyalty to service providers often costs consumers hundreds of dollars a year in inflated premiums, making policy shopping a smart avenue when evaluating money saving tips. Insurance markets change frequently, and companies often raise rates on long-term customers under the assumption they will not shop around. For example, getting competitive quotes for auto and home insurance once a year can reveal identical coverage at a noticeably lower price point.
The benefit is immediate savings on fixed overhead costs without sacrificing your safety net or legal protections. However, the trade-off is the tedious administrative work involved in comparing deductibles, coverage limits, and fine print across multiple providers. Rates, rules, and taxes differ by country and state, and switching too frequently can sometimes forfeit loyalty perks. The key takeaway is that insurance is a commodity, and treating it as such prevents you from paying an invisible loyalty tax.
9. Utilize High-Yield Savings Accounts for Cash Reserves
Where you store your cash matters significantly when your primary objective is accumulating wealth through reliable money saving tips. Moving your emergency fund or short-term savings out of a traditional brick-and-mortar bank—which often pays negligible interest—and into a high-yield savings account maximizes your returns. For example, keeping ten thousand dollars in an account yielding 4.5% APY generates four hundred and fifty dollars in annual interest, compared to just a few dollars at a traditional institution.
These accounts offer liquidity, federally insured security up to standard limits, and steady growth without market risk. The trade-off is that interest rates fluctuate with broader macroeconomic conditions, meaning your yields can drop when central banks lower rates. When researching options, compare provider fees, minimum balance requirements, and digital interfaces. The key takeaway is that your liquid cash should always work hard for you rather than sitting idle in a zero-yield account.
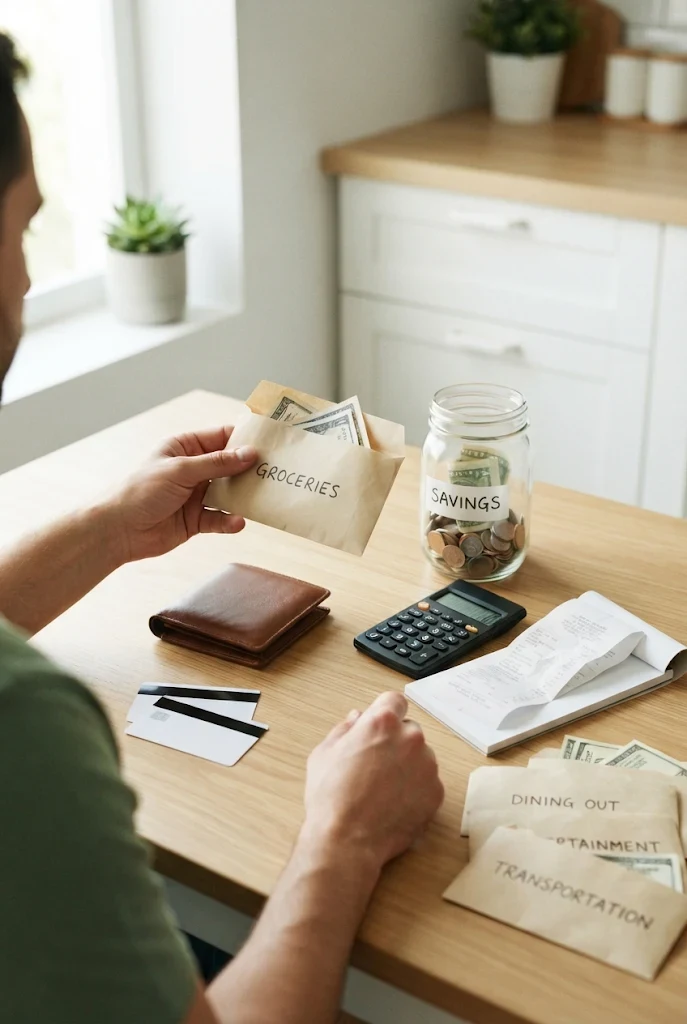
10. Implement the Cash Envelope System for Problem Categories
Behavioral spending limits can be enforced effectively by switching from digital payments to physical currency for temptation-prone budget categories. The cash envelope system involves withdrawing a fixed amount of physical cash at the start of the month for categories like dining out or entertainment, and spending strictly from that envelope until it is empty. For example, allocating one hundred and fifty dollars in cash for weekend outings ensures that once the bills are gone, your spending stops immediately.
This tactile method creates a powerful psychological barrier against overspending because handing over physical paper money hurts more than swiping a piece of plastic. The main trade-off is the inconvenience of carrying cash, visiting ATMs, and losing out on credit card rewards or fraud protection. The key takeaway is that physical limitations can successfully curb psychological spending habits when digital tools fail.
11. Negotiate Your Utility and Service Bills
Service providers rarely reward customer loyalty voluntarily, making periodic negotiation a lucrative tactic for anyone applying advanced money saving tips to fixed monthly overhead. Internet providers, mobile carriers, and cable companies frequently run unadvertised promotional rates or retention discounts that customer service representatives can apply if asked. For example, calling your internet provider to discuss a competitor’s lower introductory rate can result in a permanent thirty-dollar monthly discount.
Successful negotiation lowers your baseline living expenses with zero reduction in your standard of living. The trade-off is that the process requires patience, navigating automated phone trees, and sometimes enduring awkward retention pitches. The key takeaway is that a twenty-minute phone call can yield an hourly return that rivals your actual workday wage.
12. Buy Quality Secondhand Goods
Avoiding retail markups on durable items is a sustainable method featured among popular money saving tips for furniture, clothing, books, and electronics. Platforms dedicated to local resale and thrift stores offer high-quality items that have depreciated drastically despite remaining in excellent condition. For example, purchasing a solid wood dining table secondhand instead of buying new can easily cut the cost in half.
Buying used is environmentally friendly and often grants access to superior craftsmanship that modern flat-pack furniture cannot match. The primary trade-off is the lack of standard manufacturer warranties, the absence of return policies, and the time required to inspect items and arrange pickup. The key takeaway is that depreciation works in your favor when you let someone else absorb the initial value drop.
13. Audit and Lower Your Energy Consumption
Household utility bills represent a massive recurring expense that can be systematically reduced by integrating targeted money saving tips focused on energy efficiency. Simple changes like lowering your thermostat by a few degrees in winter, installing LED lightbulbs, washing clothes in cold water, and sealing window drafts make a measurable difference. For example, optimizing your home climate control settings can shave ten to fifteen percent off your monthly electric bill.
These adjustments lower your carbon footprint alongside your monthly expenditures, contributing to long-term sustainability. The trade-off is that some upgrades require upfront capital, such as purchasing programmable thermostats or energy-star appliances. The key takeaway is that energy efficiency is an ongoing habit of mindfulness that pays dividends every single billing cycle.
14. Embrace a Structured Savings Challenge
Gamifying your financial goals can transform the often tedious process of executing money saving tips into an engaging and motivating personal challenge. Popular frameworks like the 52-week challenge or micro-saving increments encourage participants to set aside incremental amounts that grow over time. For example, saving one dollar the first week, two dollars the second week, and scaling upward builds a tidy sum by the end of the year without feeling overwhelming.
Challenges provide clear psychological milestones and make habit formation fun and interactive. The trade-off is that escalating challenges can become difficult to maintain during months when unexpected expenses arise, requiring flexibility rather than rigid adherence. The key takeaway is that gamification lowers the mental barrier to entry for building a robust financial cushion.
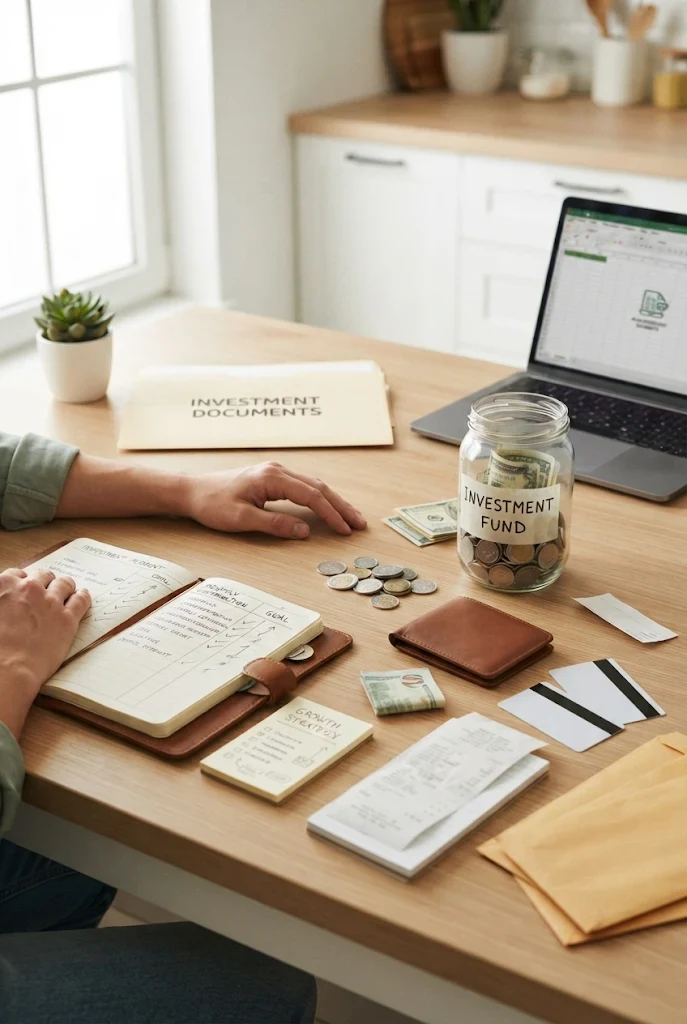
15. Automate Investment Contributions for Long-Term Growth
While short-term cash reserves are essential, true wealth building requires shifting excess funds through long-term growth vehicles to outpace inflation. Setting up automatic transfers into diversified index funds or retirement accounts ensures your surplus wealth compounds steadily over decades. For example, investing two hundred and fifty dollars a month into a broad-market index fund harnesses the historical power of compound interest for your future.
Long-term investing offers the potential for significant wealth accumulation and financial independence in retirement. The trade-off is market volatility; your portfolio value will fluctuate day-to-day, requiring emotional discipline to avoid panic-selling during economic downturns. The key takeaway is that time in the market beats timing the market, and consistency is your greatest asset.
FAQ
- What are the best money saving tips for beginners starting from scratch? Begin by tracking your expenses for thirty days to identify spending leaks, then automate a small transfer on payday to build consistency effortlessly.
- How much of my income should I allocate toward saving each month? A popular baseline is the 50/30/20 rule, which directs twenty percent of net income toward savings and debt reduction, though you can start smaller and scale up.
- Why should I use a high-yield savings account instead of a regular bank? High-yield accounts offer significantly higher interest rates, allowing your cash reserves to grow much faster while keeping your funds completely liquid.
📚 You Might Also Like
- Saving money: 15 Easy Money Tips for 2026Mastering the art of saving money begins with a clear understanding of your cash flow and consistent…
- Cheap Rings for Women: Stylish Jewelry on a BudgetFinding the perfect piece of jewelry doesn’t have to break the bank. Affordable jewelry for he…
- How to Fix a Broken Necklace: Easy DIY TipsDiscovering that your favorite piece of jewelry has snapped can be incredibly frustrating. Whether i…
- Is 5000 dollars enough for a wedding ring? 6 Things to ConsiderIs 5000 dollars enough for a wedding ring? 💍 For most couples, the answer is yes — this budget give…
- What is the normal cost of a wedding ring?What is the normal cost of a wedding ring? 💍 On average, wedding rings in the U.S. range from \$500…
The Bottom Line
Achieving financial stability and peace of mind is not about deprivation; it is about alignment, intention, and consistency. By implementing small, systematic changes—from auditing subscriptions to automating your transfers—you transform everyday money saving tips from an intimidating chore into an empowering lifestyle habit. Remember that personal finance is entirely personal; adjust these strategies to fit your unique circumstances, income level, and life stage. Consistency always triumphs over perfection, and every small step you take today builds a more secure foundation for your future.
Disclaimer: This article is for general educational purposes only, is not personal financial advice, and readers should consult a licensed professional before making financial decisions.
🛍️ Shop the Look — Best Sellers for money saving tips
Our handpicked Amazon best sellers curated specifically for money saving tips:
🔥 See More Best Sellers on Amazon →
As an Amazon Associate I earn from qualifying purchases.