Effective money saving methods are structured financial practices that individuals use to reduce unnecessary expenditures, build cash reserves, and improve long-term financial stability. Finding the right money saving methods can often feel overwhelming given the sheer volume of conflicting advice available online. However, building sustainable financial habits does not require drastic lifestyle overhauls or complex mathematics. Instead, it relies on consistent, small adjustments and clear organization. This guide breaks down practical approaches to managing your capital, reducing waste, and protecting your future.
1. Track Every Expense for 30 Days — money
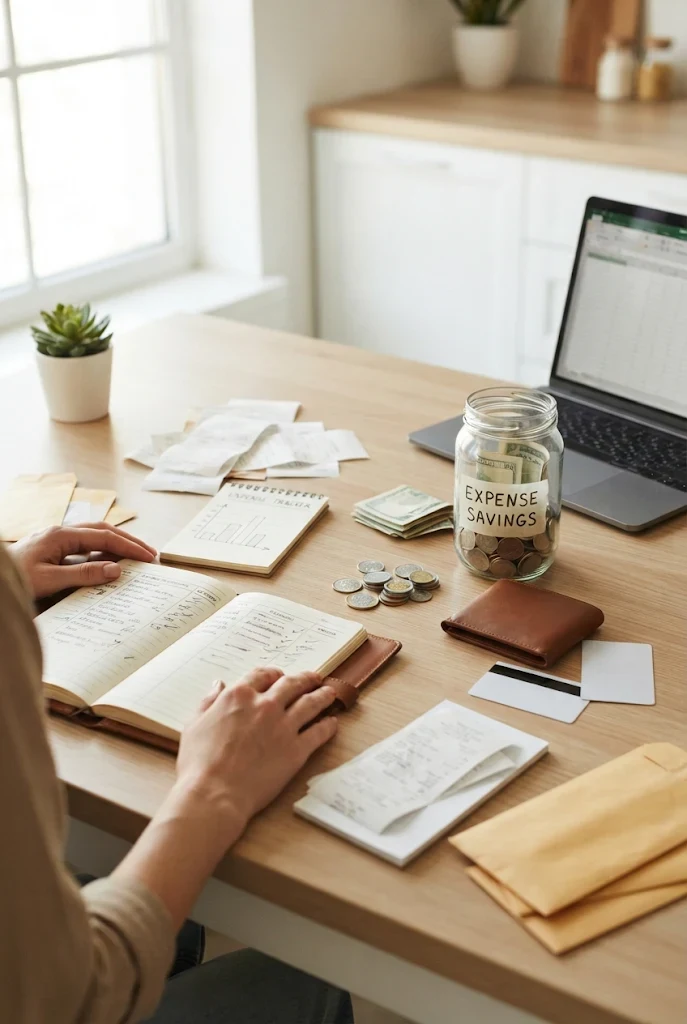
Money saving methods begin with a complete understanding of where your funds actually go each month. For example, if you spend a hypothetical $15 on convenience purchases daily, those small amounts compound quickly over time. By logging every transaction in an expense tracking notebook or digital ledger for a full month, you can identify hidden spending leaks.
The primary benefit of this tracking habit is absolute visibility into your cash flow. However, the trade-off is the significant time investment and daily discipline required to record every single receipt.
The key takeaway is that awareness precedes reduction; you cannot optimize your spending until you measure it accurately.
2. Implement the 50/30/20 Budgeting Framework — money
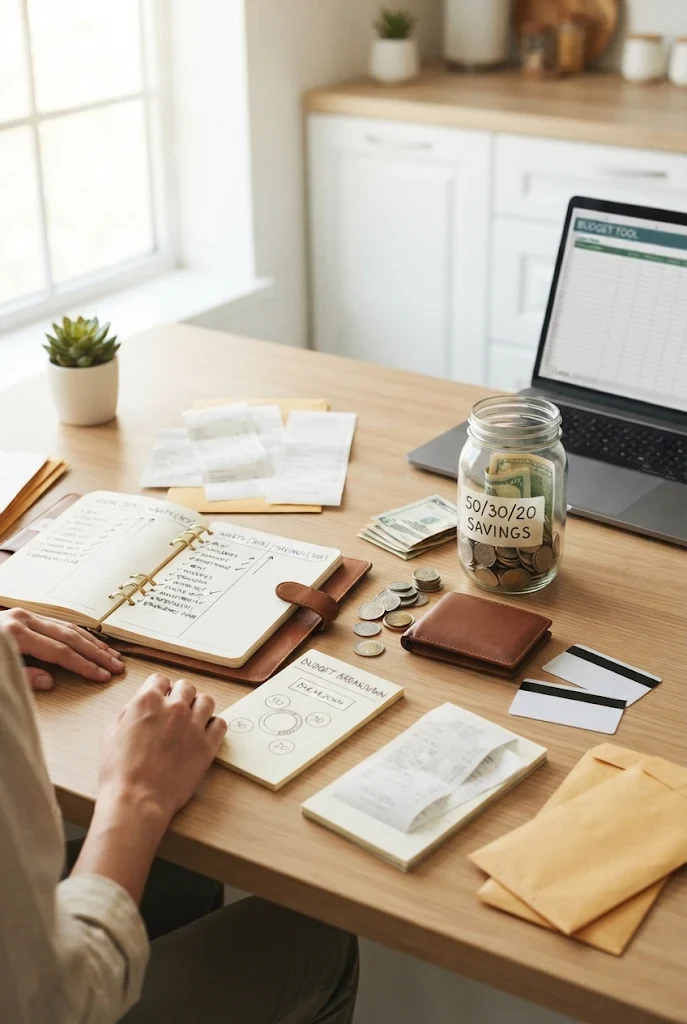
Structured budgeting frameworks provide clear boundaries for how you allocate your monthly income across distinct categories. This approach divides your net income into 50% for necessities like housing and groceries, 30% for discretionary wants, and 20% for savings and debt repayment. Utilizing a dedicated budget planner notebook helps keep these percentages on track without requiring constant manual calculation.
While this system offers a balanced approach that prevents burnout, it can be rigid if your fixed living expenses exceed the 50% threshold due to local economic conditions.
The key takeaway is that categorizing your income creates predictable boundaries that naturally curb overspending.
3. Automate Your Transfers on Payday — money
Relying on willpower alone to set money aside frequently fails when competing financial temptations arise. Setting up automatic transfers from your checking account to a savings or investment vehicle on payday ensures that funds are saved before you have the chance to spend them.
The major advantage of automation is that it removes human emotion and friction from the savings process entirely. The potential risk, however, is accidentally overdrawing your primary account if your income fluctuates or if unexpected bills hit simultaneously.
The key takeaway is that making savings automatic turns a difficult chore into a passive, background habit.
4. Build a Dedicated Emergency Fund
Unexpected expenses, such as vehicle repairs or sudden medical bills, can instantly derail financial stability if you lack a dedicated cash buffer. Maintaining a separate savings jar or distinct bank sub-account helps protect your everyday budget from these unforeseen shocks.
Having this financial cushion provides immense peace of mind and prevents the need high-interest debt during emergencies. The trade-off is that keeping cash in liquid savings accounts means missing out on the higher potential returns offered by long-term investments.
The key takeaway is that an emergency fund acts as an essential shock absorber for life’s unpredictable moments.
5. Audit and Cut Recurring Subscriptions
Monthly digital subscriptions, streaming services, and forgotten app memberships can silently drain hundreds of dollars from your accounts each year. Reviewing your bank statements every six months allows you to identify and cancel services you no longer actively use.
This cleanup provides an immediate boost to your monthly disposable income with very little ongoing effort. On the downside, you may occasionally cancel a service you actually enjoy, requiring you to resubscribe later.
The key takeaway is that regular subscription audits prevent minor convenience charges from turning into major annual waste.
6. Adopt the 48-Hour Rule for Non-Essential Purchases
Impulse buying is one of the most common obstacles to effective capital accumulation. Instituting a mandatory 48-hour waiting period before purchasing any non-essential item gives your rational mind time to overcome emotional urges.
This simple delay tactic dramatically reduces buyer’s remorse and filters out unnecessary acquisitions. However, the trade-off is that it requires patience and may cause you to miss out on genuine, time-sensitive retail discounts.
The key takeaway is that introducing friction into the buying process gives you control over spontaneous purchasing habits.
7. Master Strategic Grocery Shopping and Meal Planning
Food expenses often represent one of the most flexible yet heavily mismanaged portions of a household budget. Planning your weekly meals in advance, writing a strict shopping list, and utilizing a meal prep container set can cut food waste and dining-out costs significantly.
Planning meals saves both money and time during busy work weeks. The primary drawback is the upfront planning time required to organize recipes and inventory your pantry.
The key takeaway is that intentional meal preparation eliminates costly last-minute takeout decisions.
8. Compare Insurance Policies Annually
Auto, home, and renters insurance rates often creep upward over time, even if your personal risk profile remains completely unchanged. Requesting competing quotes from alternative providers once a year ensures you are not paying an unnecessary loyalty penalty.
The financial upside of switching providers or negotiating rates can yield substantial annual savings. The main trade-off is the administrative hassle of reviewing policy documents, coverage limits, and deductibles across different companies.
The key takeaway is that treating insurance as an annual commodity review rather than a set-and-forget bill keeps costs competitive.
9. Utilize High-Yield Savings Accounts for Cash Reserves
Leaving your short-term savings in a traditional checking account often yields virtually zero interest, causing your money to lose purchasing power over time. Moving cash reserves into high-yield savings accounts allows your idle money to generate passive interest earnings.
These accounts offer liquidity and security while outperforming traditional bank yields. The trade-off is that online-only banks may lack physical branch access, and interest rates fluctuate dynamically based on broader economic policies.
The key takeaway is that parking your cash in optimized accounts ensures your savings work harder for you.
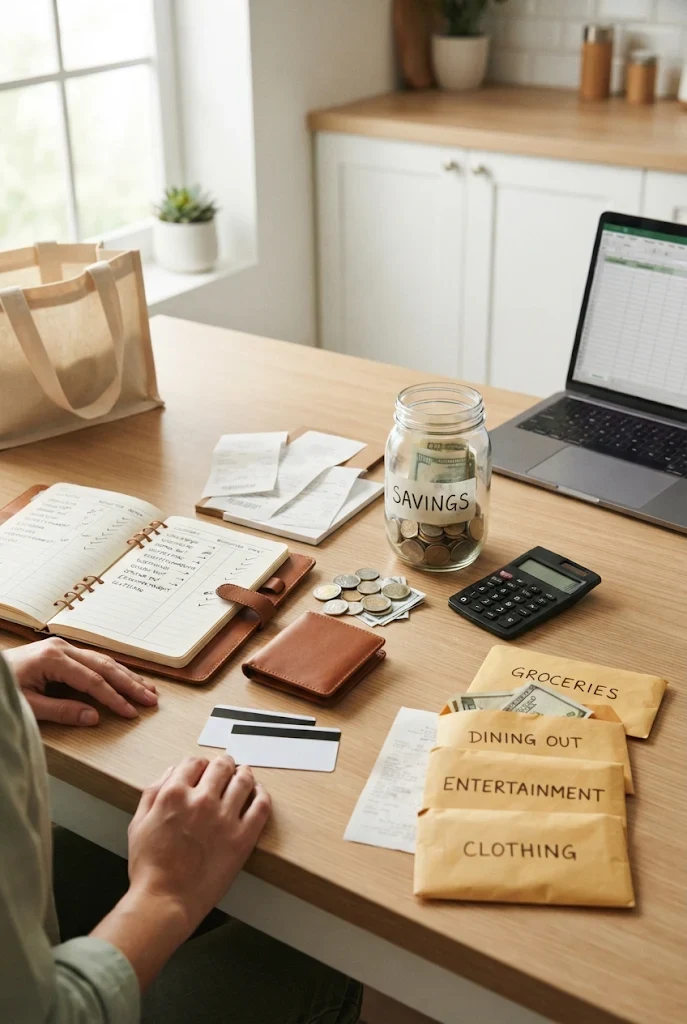
10. Implement the Cash Envelope System for Problem Categories
Digital spending makes it remarkably easy to lose track of discretionary outlays in high-temptation areas like dining or entertainment. Using a cash envelope wallet to physically allocate specific amounts of physical currency for these categories creates a hard spending ceiling.
Once the physical cash in the envelope is gone, spending in that category stops entirely for the month. The obvious disadvantage is the inconvenience of carrying physical cash and the security risks associated with losing a wallet.
The key takeaway is that physical cash creates a psychological barrier to spending that digital cards simply cannot replicate.
11. Negotiate Your Utility and Service Bills
Many household service providers, including internet, cable, and mobile phone companies, rely on customer inertia to maintain higher pricing tiers. Calling customer retention departments to negotiate lower rates or eliminate unneeded add-ons can yield immediate monthly savings.
Successful negotiations lower your fixed overhead without sacrificing your quality of service. The primary friction point is that dealing with customer service call queues can be tedious and time-consuming.
The key takeaway is that fixed utility bills are often negotiable if you are willing to ask for promotional rates.
12. Buy Quality Secondhand Goods
Purchasing brand-new items for depreciation-heavy categories, such as furniture, tools, or books, can waste significant financial resources. Sourcing durable, high-quality secondhand goods through reputable local marketplaces extends the lifecycle of items while costing a fraction of retail prices.
Buying used preserves capital and promotes sustainable consumption patterns. The trade-off is a lack of manufacturer warranties and the need to inspect items thoroughly for wear and tear.
The key takeaway is that smart secondhand shopping lets you acquire premium durability at budget-friendly prices.
13. Audit and Lower Your Energy Consumption
Household utility expenses are heavily impacted by phantom power loads, inefficient lighting, and suboptimal thermostat settings. Using an electricity usage monitor helps pinpoint energy-hogging appliances, while simple habit shifts like adjusting thermostat settings lower monthly overhead.
Lowering energy consumption reduces utility bills while shrinking your environmental footprint. The main constraint is that certain efficiency upgrades, such as replacing old appliances or installing smart thermostats, require upfront capital.
The key takeaway is that monitoring kilowatt-hour usage transforms a vague monthly utility bill into an actionable target.
14. Embrace a Structured Savings Challenge
Saving money can sometimes feel monotonous without clear milestones or gamified milestones to maintain momentum. Engaging in a structured savings challenge, such as saving incremental amounts weekly or stashing away every five-dollar bill you receive, builds consistent habits.
These challenges make the accumulation process engaging and visually rewarding. However, rigid savings challenges can be difficult to maintain if unexpected financial obligations arise mid-way through the cycle.
The key takeaway is that turning financial discipline into an engaging challenge fosters long-term consistency.
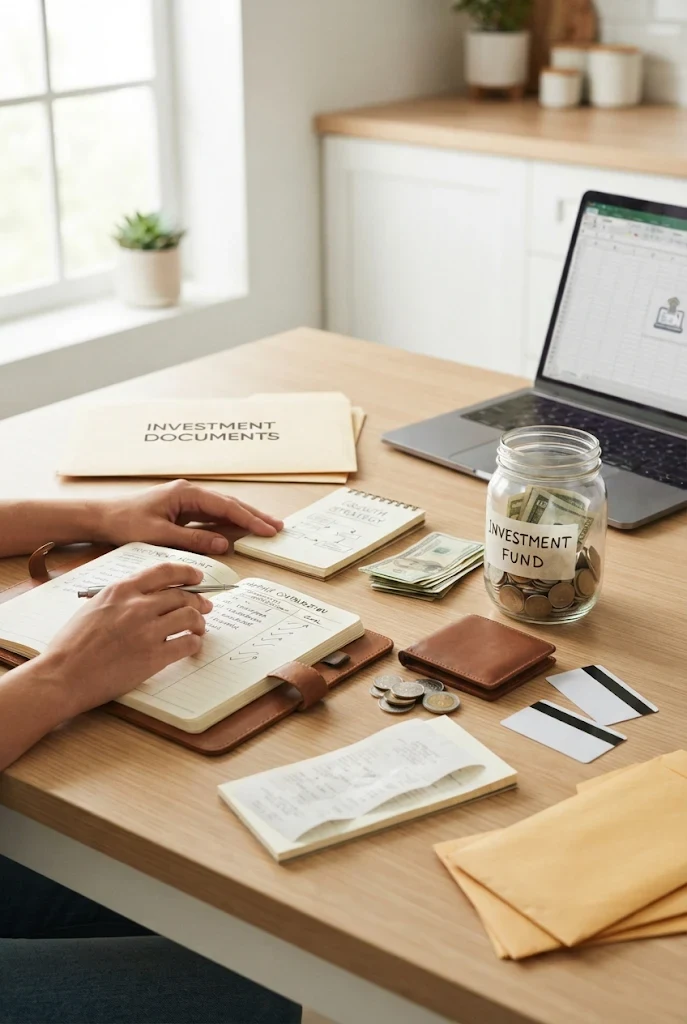
15. Automate Investment Contributions for Long-Term Growth
Relying solely on cash savings leaves your wealth vulnerable to inflation over extended periods. Directing surplus funds into diversified, low-cost investment portfolios through automated monthly contributions harnesses the power of compounding growth.
Automated investing builds wealth steadily over decades without requiring active market timing. The unavoidable trade-off is market volatility, as investment portfolios experience short-term fluctuations and temporary downturns.
The key takeaway is that consistent, automated investing bridges the gap between short-term savings and long-term financial security.
FAQ
What are the best money saving methods for beginners?
Beginner-friendly approaches include tracking expenses for thirty days, automating payday transfers, and cutting unused recurring subscriptions.
How can I save money when living on a tight income?
Focus on high-impact variable expenses by implementing meal planning, negotiating utility bills, and using the cash envelope system for discretionary spending.
Why do traditional budgeting methods fail for most people?
Budgets often fail because they are overly restrictive, rely too heavily on manual tracking, or lack automated systems to remove human friction.
📚 You Might Also Like
- How to Fix a Broken Necklace: Easy DIY TipsDiscovering that your favorite piece of jewelry has snapped can be incredibly frustrating. Whether i…
The Bottom Line
Mastering your personal finances does not require perfection, extreme deprivation, or complex financial engineering. By implementing structured money saving methods, auditing your fixed expenses, and automating your savings routines, you can build a resilient financial foundation over time. Financial wellness is built through small, consistent choices rather than single dramatic gestures. Focus on steady progress, review your systems periodically, and adapt your approach as your life circumstances evolve.
Disclaimer: This article is for general educational purposes only, is not personal financial advice, and readers should consult a licensed professional before making financial decisions.
🛍️ Shop the Look — Best Sellers for money saving methods
Our handpicked Amazon best sellers curated specifically for money saving methods:
🔥 See More Best Sellers on Amazon →
As an Amazon Associate I earn from qualifying purchases.