Embarking on a money saving challenge is a structured, practical approach to building financial resilience and improving your everyday money management skills. A money saving challenge is a gamified framework that helps individuals set aside predetermined amounts of cash over a specific timeframe to reach short-term and long-term goals. While building wealth takes time, utilizing a systematic money saving challenge can make the process feel much more manageable.
1. Choose a Flexible Framework — money
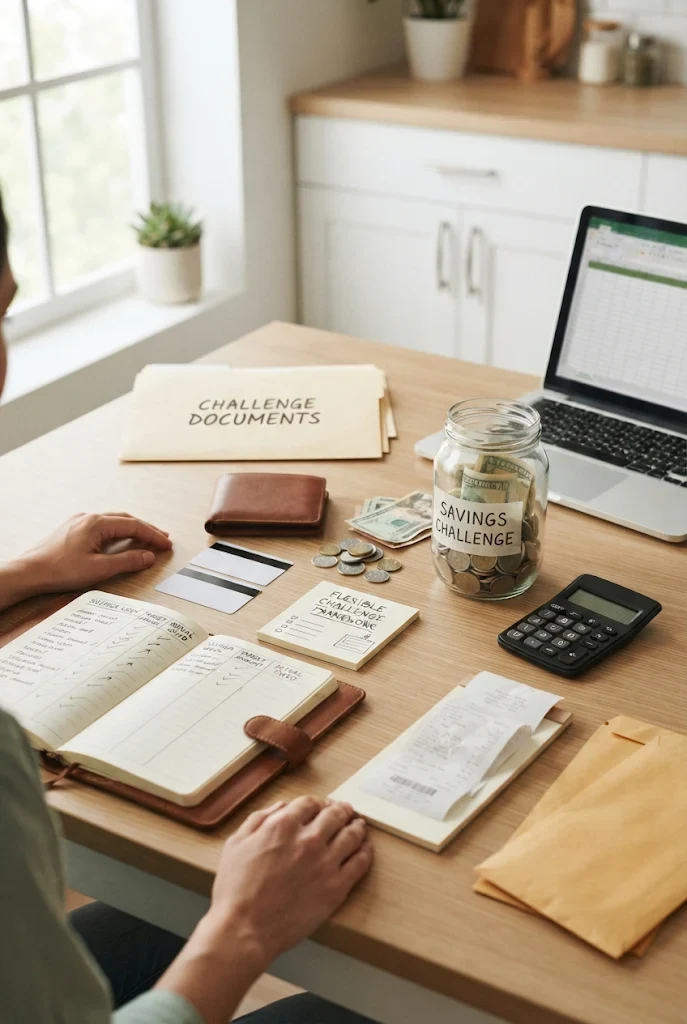
Choosing the right structure is essential for any successful money saving challenge. Every individual has different income flows, which means a rigid daily savings target may not work for everyone. For example, some participants prefer weekly milestones, while others prefer monthly contributions. The key benefit of a flexible framework is that it adapts to your unique cash flow without causing unnecessary financial stress.
However, a major trade-off is that extreme flexibility can sometimes lead to procrastination if you lack strict personal accountability. To combat this, you can use a money saving challenge printable to visually map out your targets on your desk calendar. Behavioral consistency relies heavily on keeping your goals visible and straightforward.
The key takeaway is that selecting a framework tailored to your income schedule ensures long-term adherence.
2. Automate Your Weekly Transfers — money
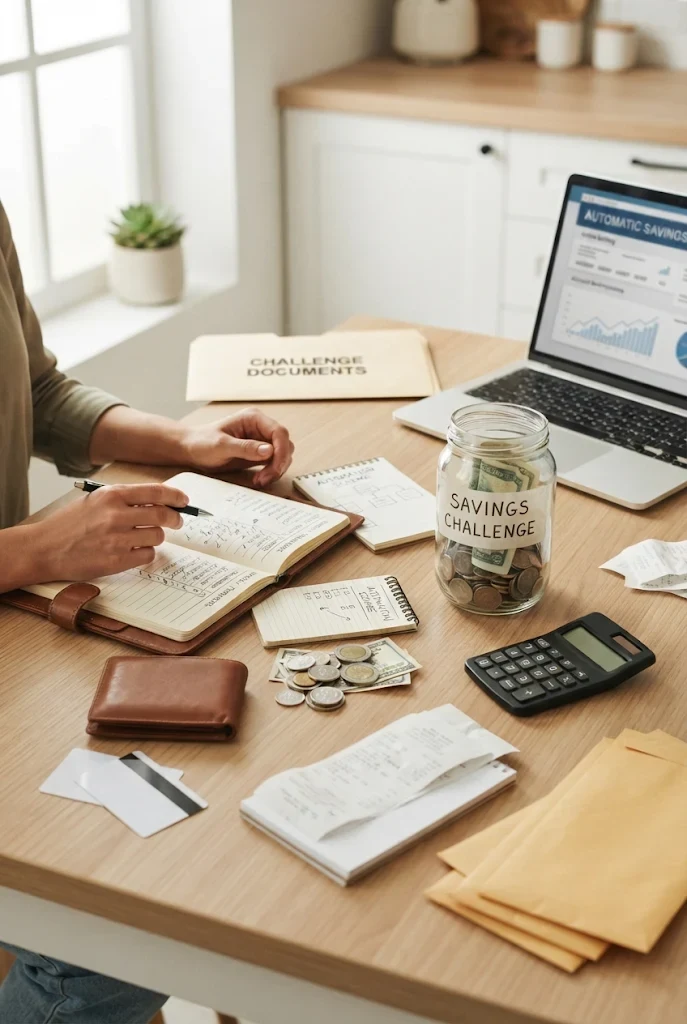
Automating your deposits removes the friction of manual transfers during a money saving challenge. When your funds move automatically from your checking account to a designated savings sub-account on payday, you eliminate the temptation to spend that money elsewhere. This approach relies on set-and-forget mechanics to keep your momentum steady.
The primary benefit is hands-free consistency, meaning you do not have to rely purely on willpower every week. The risk, however, is that automated transfers can occasionally trigger overdraft fees if your checking account balance dips unexpectedly. Always keep a buffer amount in your primary account to prevent accidental shortfalls.
The key takeaway is that automation protects your savings goals from impulsive everyday spending.
3. Implement the 52-Week Incremental Model — money
The 52-week incremental model is a classic money saving challenge where you save a small, increasing amount of money each week over the course of a year. For example, you might start by setting aside a single dollar in week one, two dollars in week two, and so on. This gradual escalation allows your budget to adjust organically over time.
The main advantage is that it introduces you to saving in very small, low-pressure increments. The trade-off appears late in the year when the weekly amounts grow larger, which can coincide with high-spending holiday seasons. Proper planning is required to ensure your December cash flow can handle those peak contributions.
The key takeaway is that incremental scaling builds strong saving habits without overwhelming your early-stage budget.
4. Try a Bi-Weekly Fixed-Amount Approach
A bi-weekly fixed-amount model simplifies a money saving challenge by dedicating a flat, repeatable sum from every paycheck. Instead of calculating fluctuating weekly rates, you commit to moving a predictable figure—for example, fifty dollars—into your reserve bucket every two weeks. This matches the payroll cycles of many modern workers.
The benefit is extreme predictability, making it easy to align your savings directly with your fixed utility and grocery expenses. The downside is that it lacks the gamified excitement of escalating targets, which some participants find less engaging. You can supplement this method by using a savings challenge tracker to color in completed milestones.
The key takeaway is that fixed bi-weekly contributions provide steady, predictable growth for your cash reserves.
5. Digitize Your Tracking Methods
Transitioning to digital tools can modernize any money saving challenge for tech-oriented savers. Utilizing a dedicated spreadsheet or a money saving challenge app allows you to monitor your progress in real-time on your smartphone or laptop. These digital platforms often send push notifications to remind you of upcoming contribution deadlines.
The primary benefit is instant data visibility and automated chart generation, which helps you spot spending leaks quickly. Conversely, relying solely on screens can sometimes disconnect you from the tangible reality of your finances. Many experts recommend pairing digital tools with a physical money saving challenge box to keep cash handling grounded.
The key takeaway is that digital trackers offer precise analytics while requiring minimal manual maintenance.
6. Engage in a Partnered Savings Journey
A shared money saving challenge turns personal finance into a collaborative team effort. Whether participating with a spouse, family member, or roommate, working together fosters mutual encouragement and accountability. You can establish shared milestones, such as funding a household repair project or a holiday travel fund.
The major benefit is built-in emotional support, which significantly lowers the drop-out rate during difficult financial weeks. The trade-off involves communication hurdles; if one partner faces an unexpected expense, it can stall the joint progress. Establishing open financial communication upfront ensures both parties remain aligned.
The key takeaway is that partnering up increases motivation and shared accountability throughout the journey.
7. Adopt the Spare Change Round-Up Rule
Rounding up everyday card purchases is a passive style of money saving challenge that operates quietly in the background. Many modern banking applications automatically round transactions up to the nearest dollar and sweep the difference into a digital savings vault. For example, a purchase costing four dollars and fifty cents rounds up to five dollars, depositing fifty cents into your reserve.
The benefit is effortless accumulation; you build savings micro-incrementally without altering your lifestyle. The trade-off is that these tiny amounts accumulate slowly, meaning it cannot replace aggressive, intentional budgeting for large goals. It serves best as a complementary booster to your primary saving strategy.
The key takeaway is that micro-savings round-ups turn routine purchases into passive contributions over time.
8. Clear Out Clutter With a No-Spend Weekend
A weekend no-spend rule functions as an intense, short-term money saving challenge designed to reset your consumer habits. During a designated Friday-to-Sunday window, you commit to spending zero dollars on non-essential items, entertainment, or dining out. You rely entirely on pantry staples and free local activities, such as walking in public parks.
The advantage is an immediate halt to impulse spending and a heightened awareness of psychological triggers. The risk is social friction if your restriction conflicts with pre-existing family or community plans. Careful scheduling ensures you can participate without feeling socially isolated.
The key takeaway is that brief spending blackouts help break impulsive consumer cycles and preserve cash.
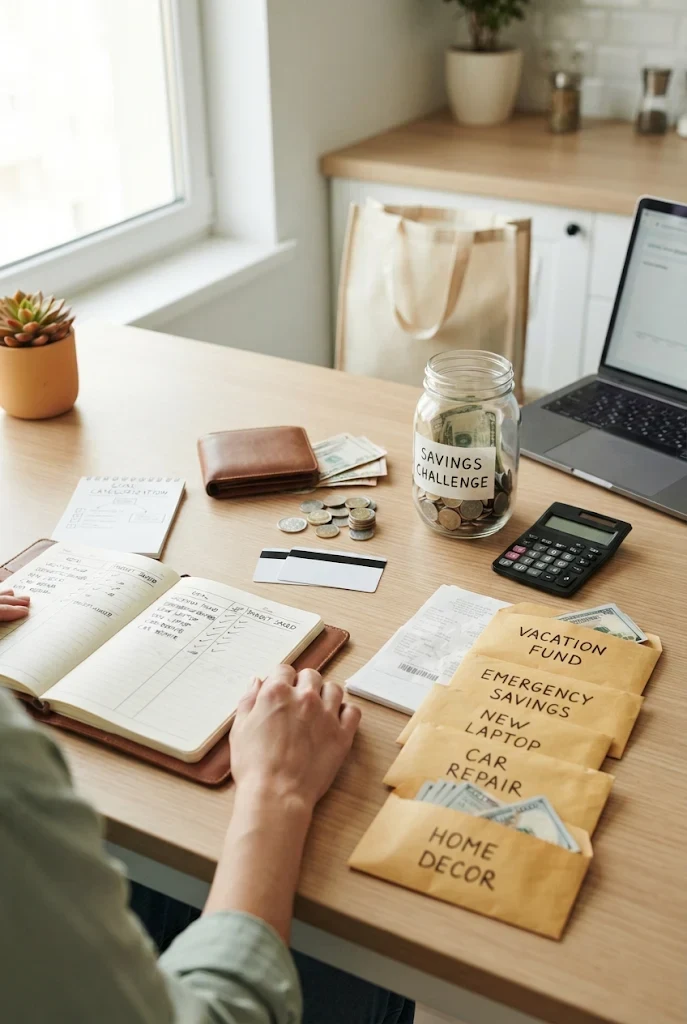
9. Categorize Your Goals with Visual Envelopes
Assigning specific cash envelopes to a money saving challenge provides clear boundaries for your discretionary funds. By labeling physical paper envelopes or dedicated folders with specific targets—such as automotive maintenance or clothing—you create a tangible barrier against overspending. When an envelope is empty, discretionary spending in that category stops.
The main benefit is psychological clarity, as physical limits prevent the blurred lines common with plastic cards. The trade-off is the inherent security risk of keeping physical cash at home rather than in an insured financial institution. Keeping only small working balances at hand mitigates this vulnerability.
The key takeaway is that physical categorization creates strict psychological boundaries for your discretionary money.
10. Audit and Pause Inactive Subscriptions
Conducting a subscription audit is an impactful money saving challenge booster that targets recurring digital leaks.Review your bank statements to identify streaming services,software licenses,and delivery clubs that you rarely utilize.Canceling even two unneeded monthly subscriptions can instantly redirect funds toward your core savings goals.
The benefit is high leverage; a one-time cancellation yields recurring savings month after month. The risk is accidentally cutting a service that family members actively rely upon, leading to friction. Always cross-check household usage before finalizing any cancellation requests.
The key takeaway is that pruning forgotten subscriptions frees up reliable cash flow with zero lifestyle sacrifice.
11. Optimize Grocery Spending Through Batch Cooking
Mastering meal planning transforms food consumption into a practical money saving challenge. By taking inventory of your pantry, building a strict shopping list, and preparing batches of meals ahead of time, you drastically reduce expensive restaurant deliveries and impulse supermarket purchases.
The primary advantage is substantial monthly savings on food costs while improving nutritional intake. The trade-off is the upfront investment of time required for weekly grocery preparation and kitchen cleanup. Establishing a meal prep routine helps streamline this process into a manageable habit.
The key takeaway is that intentional meal planning curbs high food expenditures and minimizes household waste.
12. Enforce a Cooling-Off Period for Purchases
Implementing a mandatory waiting period acts as a psychological safeguard during any money saving challenge. When you feel the urge to buy a non-essential item online or in a store, force yourself to wait forty-eight hours before pulling the trigger. This pause allows emotional excitement to fade, revealing whether the item is truly necessary.
The benefit is a sharp reduction in buyer’s remorse and impulsive credit card charges. The trade-off is that time-sensitive sales may expire during your waiting window, though missing a discount on an unneeded item is rarely a true loss. Patience remains your best financial defense.
The key takeaway is that forced waiting periods separate genuine needs from fleeting emotional impulses.
13. Leverage High-Yield Accounts for Stash Growth
Parking your accumulated funds in a high-yield savings account maximizes the efficiency of your money saving challenge. Traditional checking accounts often offer negligible interest, whereas specialized cash reserve accounts provide competitive annual percentage yields (APY) that help your money grow faster over time.
The major benefit is passive interest earnings on capital that would otherwise sit idle. The trade-off includes potential account maintenance fees or minimum balance requirements that vary across financial institutions. Always review the fee structures and terms before opening a new account.
The key takeaway is that high-yield accounts ensure your saved capital works harder through compounding interest.
14. Scale Your Success with Seasonal Resets
Conducting quarterly or seasonal financial resets keeps a long-term money saving challenge vibrant and engaging. As your income or living expenses shift throughout the year, review your budget templates and adjust your target numbers upward or downward accordingly. Spring and autumn transitions offer ideal natural checkpoints for this review.
The benefit is continuous alignment between your financial habits and your current life circumstances. The risk is burnout if your targets become overly aggressive after a temporary windfall. Maintaining balance prevents financial fatigue.
The key takeaway is that regular seasonal adjustments keep your savings strategy realistic and sustainable.
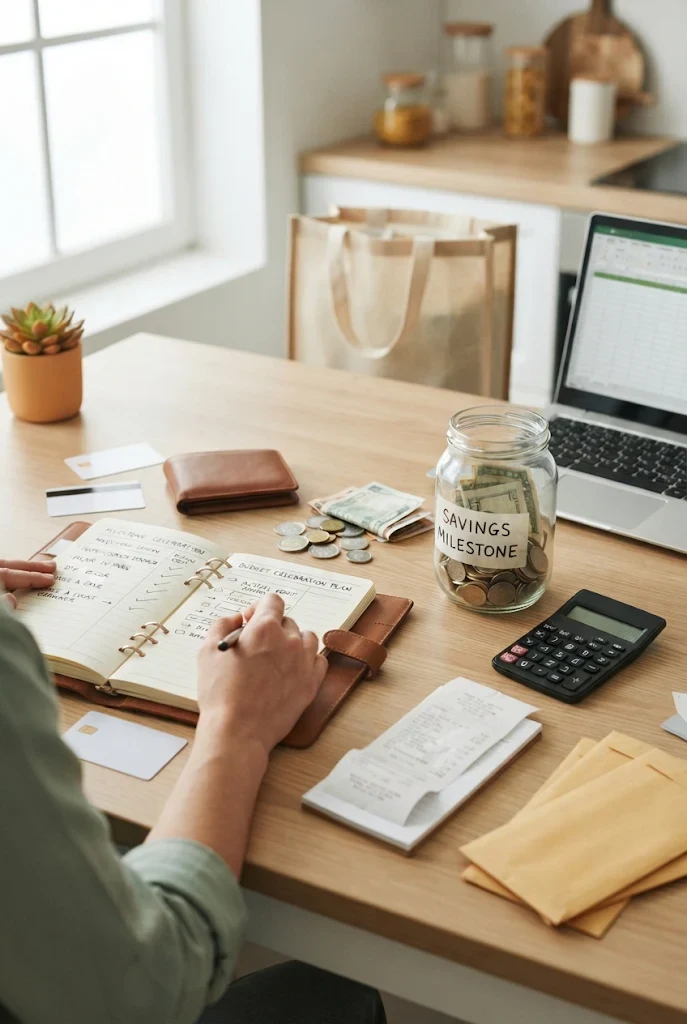
15. Celebrate Milestones Without Breaking the Budget
Acknowledging milestones successfully is the final pillar of any rewarding money saving challenge. When you reach a major savings checkpoint—such as completing a 30-day streak or hitting your mid-year target—reward yourself with a modest, low-cost treat rather than an expensive shopping spree.
The benefit is positive reinforcement, which strengthens your psychological commitment to good financial habits. The trade-off is the danger of letting a celebration trigger a slippery slope back into old spending patterns. Keep your celebrations intentional and aligned with your broader goals.
The key takeaway is that mindful rewards reinforce positive financial behaviors without derailing your progress.
FAQ
- What is a money saving challenge?
A money saving challenge is a structured, often gamified framework designed to help individuals systematically set aside cash reserves over a defined period. - How do I start a money saving challenge?
You start by selecting a framework that matches your income, setting a clear target goal, and utilizing trackers or automation to maintain consistency. - Why should I use a money saving challenge?
Using a structured challenge builds financial discipline, smooths out cash flow fluctuations, and helps establish long-term savings habits without feeling overwhelmed.
📚 You Might Also Like
- Money saving methods: 15 Smart Money Tips for 2026Effective money saving methods are structured financial practices that individuals use to reduce unn…
- Money saving tips: 15 Practical Money Tips for 2026Mastering effective money saving tips begins with understanding your daily cash flow and establishin…
- Saving money: 15 Easy Money Tips for 2026Mastering the art of saving money begins with a clear understanding of your cash flow and consistent…
The Bottom Line
Taking control of your finances does not require complex financial engineering or drastic lifestyle overhauls. By introducing a structured framework, automating your transfers, and maintaining steady accountability, you can build meaningful cash reserves over time. Remember that consistency always outweighs intensity when building lasting security. Approach your financial journey with patience, adapt your strategies to fit your personal circumstances, and celebrate small victories along the way.
Disclaimer: This article is for general educational purposes only, is not personal financial advice, and readers should consult a licensed professional before making financial decisions.
🛍️ Shop the Look — Best Sellers for money saving challenge
Our handpicked Amazon best sellers curated specifically for money saving challenge:
🔥 See More Best Sellers on Amazon →
As an Amazon Associate I earn from qualifying purchases.